A month-end close checklist for medical practices
Published by: QonsultFirm · Prepared with AI assistance · Reviewed by: Alfred Hatmal, BA, CMA, MBA, EA · Last reviewed: September 12, 2026
A useful close gives practice leaders more than a profit-and-loss statement. It explains which balances have been checked, what changed and which questions still need an answer.
Use this checklist to agree the evidence, responsibilities and unresolved items that belong in your practice’s monthly reporting package. Adapt it to the reporting basis, entities, systems and services in your engagement.
Start with a definition of complete
Define the period and accounts being reviewed. Identify who supplies the source information, who prepares the work and who reviews it. The close timetable should reflect when reliable bank, payroll and billing information becomes available.
Missing information should remain visible. Record what is missing and how it could affect the reports rather than presenting an incomplete package as final.
The evidence sequence
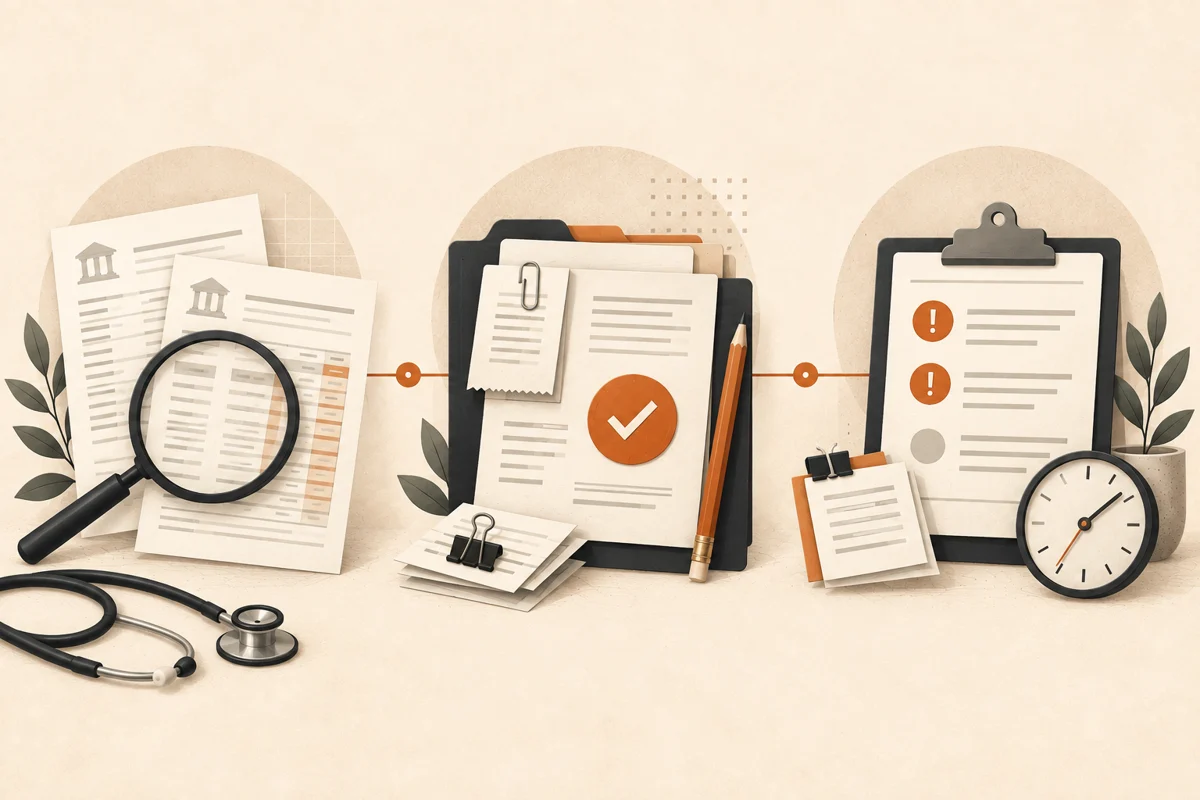
- Gather evidence: agree the cutoff and collect the source reports.
- Reconcile accounts: connect recorded balances with supporting information.
- Review exceptions: explain differences and obtain approval for corrections.
- Explain results: deliver the reporting package with limitations and next actions.
The monthly close checklist
Use the final column to record completion or a specific open item. A checkmark should mean the supporting work has been completed and reviewed as agreed.
| Check | Work to review | Evidence to retain | Status / open item |
|---|---|---|---|
| Establish cutoff | Confirm the reporting period, entities and source-report dates. | Close checklist and missing-information list. | To complete |
| Reconcile cash | Compare bank and credit-card activity and balances with the ledger. | Reconciliations and explanations of outstanding items. | To complete |
| Connect collections | Explain differences between billing receipts and deposits, including timing, fees and refunds. | Reconciliation bridge and exception record. | To complete |
| Review payroll | Compare payroll reports with cash movements, classifications and related liabilities. | Payroll support and reconciliation notes. | To complete |
| Review material balances | Support receivables, payables and other material accounts as applicable to the reporting basis. | Account schedules and approved corrections. | To complete |
| Explain performance | Review material movements against the prior period or budget. | Explanations, limitations and action owners. | To complete |
Explain differences instead of forcing agreement
A billing report and a bank statement can show different totals for legitimate reasons. Payments may be posted in one period and deposited in another; fees and refunds can also affect the comparison.
Do not post an unexplained adjustment simply to make two reports agree. Record the difference, source, timing and person responsible for follow-up. For the detailed method, read Revenue reconciliation: from billing reports to the bank.
Review the balance sheet as well as profit
A familiar-looking profit figure does not establish that every account is correct. Old reconciling items, payroll liabilities and unexplained opening balances can remain unresolved. Ask for support for material balances and explanations of changes.
Keep operating costs, owner distributions and financing activity appropriately distinguished under the practice’s accounting policies. State the reporting basis: cash and accrual reports can tell different timing stories.
Keep open items actionable
Separate an accounting correction from a business explanation. A miscoded invoice may need an approved classification correction; higher staffing costs may instead reflect a real operating change. Record material corrections and identify prior-period revisions so comparisons use the appropriate report versions.
For each unresolved item, retain:
- The question and supporting evidence still needed.
- The affected account or report and the potential effect, if known.
- The responsible person and an agreed follow-up date.
- The resolution evidence and review status.
Before calling the close complete
- The reporting period and basis are identified.
- Agreed reconciliations and material account reviews are supported.
- Corrections have the required approvals.
- Open items and their known limitations are disclosed.
- The reporting package and next actions have been reviewed with the appropriate people.
Review late inputs and recurring exceptions before the next close. If opening balances cannot be supported or several prior periods remain unreconciled, identify a separate cleanup scope rather than hiding the backlog within routine monthly work.
Limits of this checklist: This is general educational guidance, not a complete procedure for every practice or an assurance opinion. The necessary work depends on the reporting basis, systems, records and agreed engagement. Completing the checklist alone does not establish that the financial statements are free of error.
Put the checklist into your monthly workflow
Explore healthcare accounting support to understand how reconciliations, review and financial statements can fit into an agreed monthly scope.
Talk through your medical group’s next financial step.
Schedule a complimentary 30-minute consultation with QonsultFirm.
Book a Consultation