How to compare profitability across medical-practice locations
A group total can conceal very different location economics. A useful site comparison explains revenue, direct costs and shared overhead on a consistent basis.
Decide what the comparison is supposed to explain
Before creating a location ranking, identify the decision. Leadership may be evaluating staffing, space utilization, a lease renewal or a new site. Each question requires context beyond a single margin.
Define the locations, reporting period and accounting basis. Make sure the group view reconciles with the site schedules after appropriate shared or unallocated items. If two systems assign the same transaction to different sites, resolve that mapping before interpreting the difference as an operating result.
Separate direct costs from shared overhead
Direct site costs may include expenses that can be reasonably traced to a specific location. Shared administration, central software or leadership costs may need a documented allocation. The exact treatment depends on the practice and the purpose of the report.
Show the result before shared overhead and again after the allocation. This lets leadership see both the site’s direct contribution and the effect of the allocation method. Do not describe the first number as final profit if material costs remain outside it.
Illustrative monthly comparison — amounts in $000
| Measure | Location A | Location B |
|---|---|---|
| Revenue on the same reporting basis | 300 | 200 |
| Direct operating costs | (210) | (130) |
| Contribution before shared overhead | 90 | 70 |
| Allocated shared overhead | (45) | (35) |
| Estimated operating profit after allocation | 45 | 35 |
| Estimated operating margin | 15% | 17.5% |
Original illustrative example, not client results or a benchmark. The example treats all shared overhead shown as allocated and uses the same revenue basis for both sites. Actual reports must identify excluded or unallocated items.
Avoid drawing the wrong conclusion from the example
Location A produces more estimated profit dollars, while Location B shows a higher percentage margin. Neither fact alone establishes which site is better or where the practice should invest. The sites may have different capacity, lease terms, service mix or growth stages.
An older location operating near capacity and a recently opened site still building volume should not be interpreted without that context. A margin table starts the discussion; it should not end it.
Choose and document an allocation basis
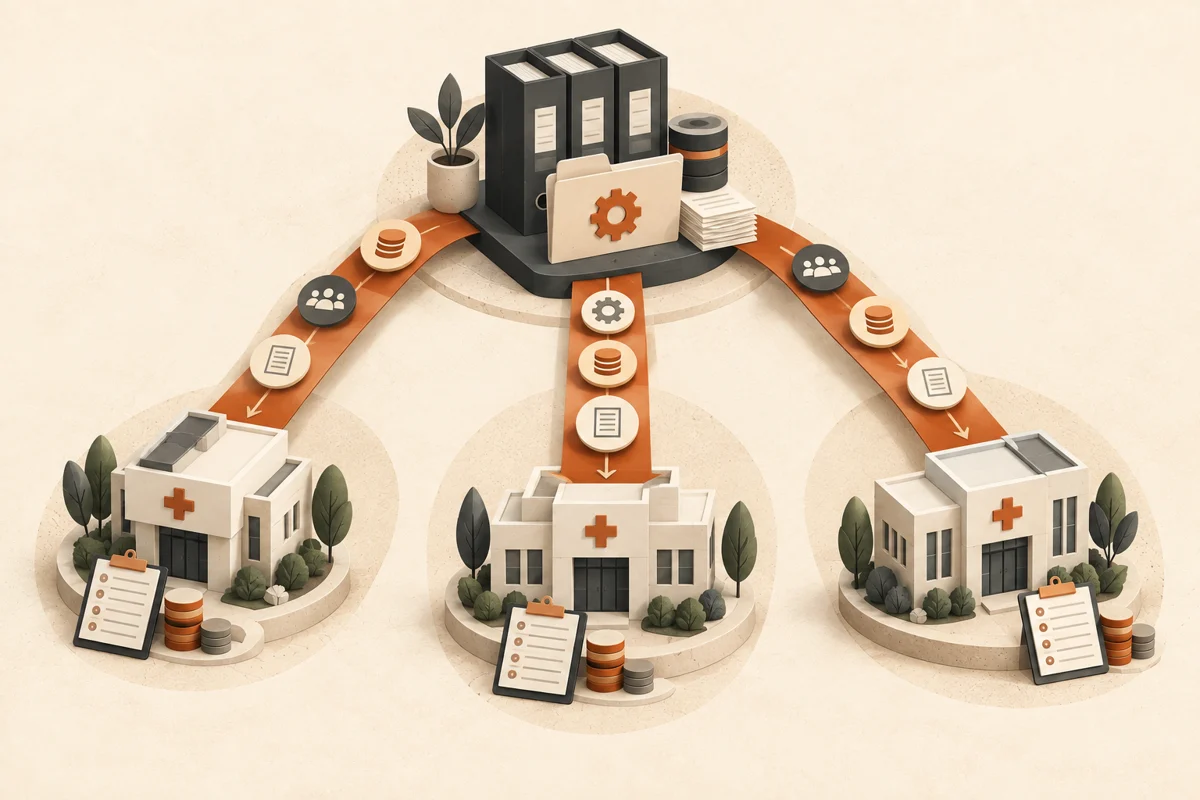
Keep direct location costs separate.
Use a reasonable, consistent basis suited to the cost and decision.
Explain changes in method and reconcile to the group.
The report should explain how shared expenses are distributed. Different cost categories may require different drivers. A space-related expense may be considered differently from a cost driven by staffing or transactions. The objective is a reasonable, consistent method suited to the decision—not whichever method produces the preferred answer.
If management changes the allocation method, explain the change and consider a comparable prior-period view. Otherwise, a location may appear to improve or deteriorate even though its operations have not changed.
Add operating context to the financial review
Review clinical availability, staffing, payer mix, collection timing and one-time costs where relevant and supported by data. Distinguish a change in revenue recognition from a change in cash collections. Identify costs that leadership can influence at the site level and those controlled centrally.
Keep transfers between legal entities separate from new group revenue, and agree the appropriate consolidation treatment with the accounting reviewer. A location report that does not connect back to the group can create conflicting versions of performance.
Finish with a question and an owner
A useful review might ask whether staffing matches current capacity, whether coding needs correction or whether a lease decision needs a separate forecast. Assign a person to investigate and state what information is needed.
Maintain consistent definitions over time. The value of location reporting comes from understanding changes and supporting decisions, not simply producing a monthly league table.
Talk through your medical group’s next financial step.
Schedule a complimentary 30-minute consultation with QonsultFirm.
Book a Consultation